CFC reduces 20-year total freighter forecast by 2.2% to 3,867 units
Cargo Facts Symposium

NASHVILLE, Tenn. — Cargo Facts Consulting has reduced its 20-year freighter forecast by 2.2% percent to a total of 3,867 freighters in service by 2045.
“That’s due to a number of factors that include the overall economics, the production rates on an aircraft, conversion rates, certification, demand, and the developments on the passenger aircraft supply,” Senior Analyst Jeff Lee said in a presentation Oct. 21, the first day of Cargo Facts Symposium.
About 2,851 additional aircraft will be added to the current fleet, most of them being conversions, he added. Of those, 691 will be new aircraft, and 2,160 will be conversions.
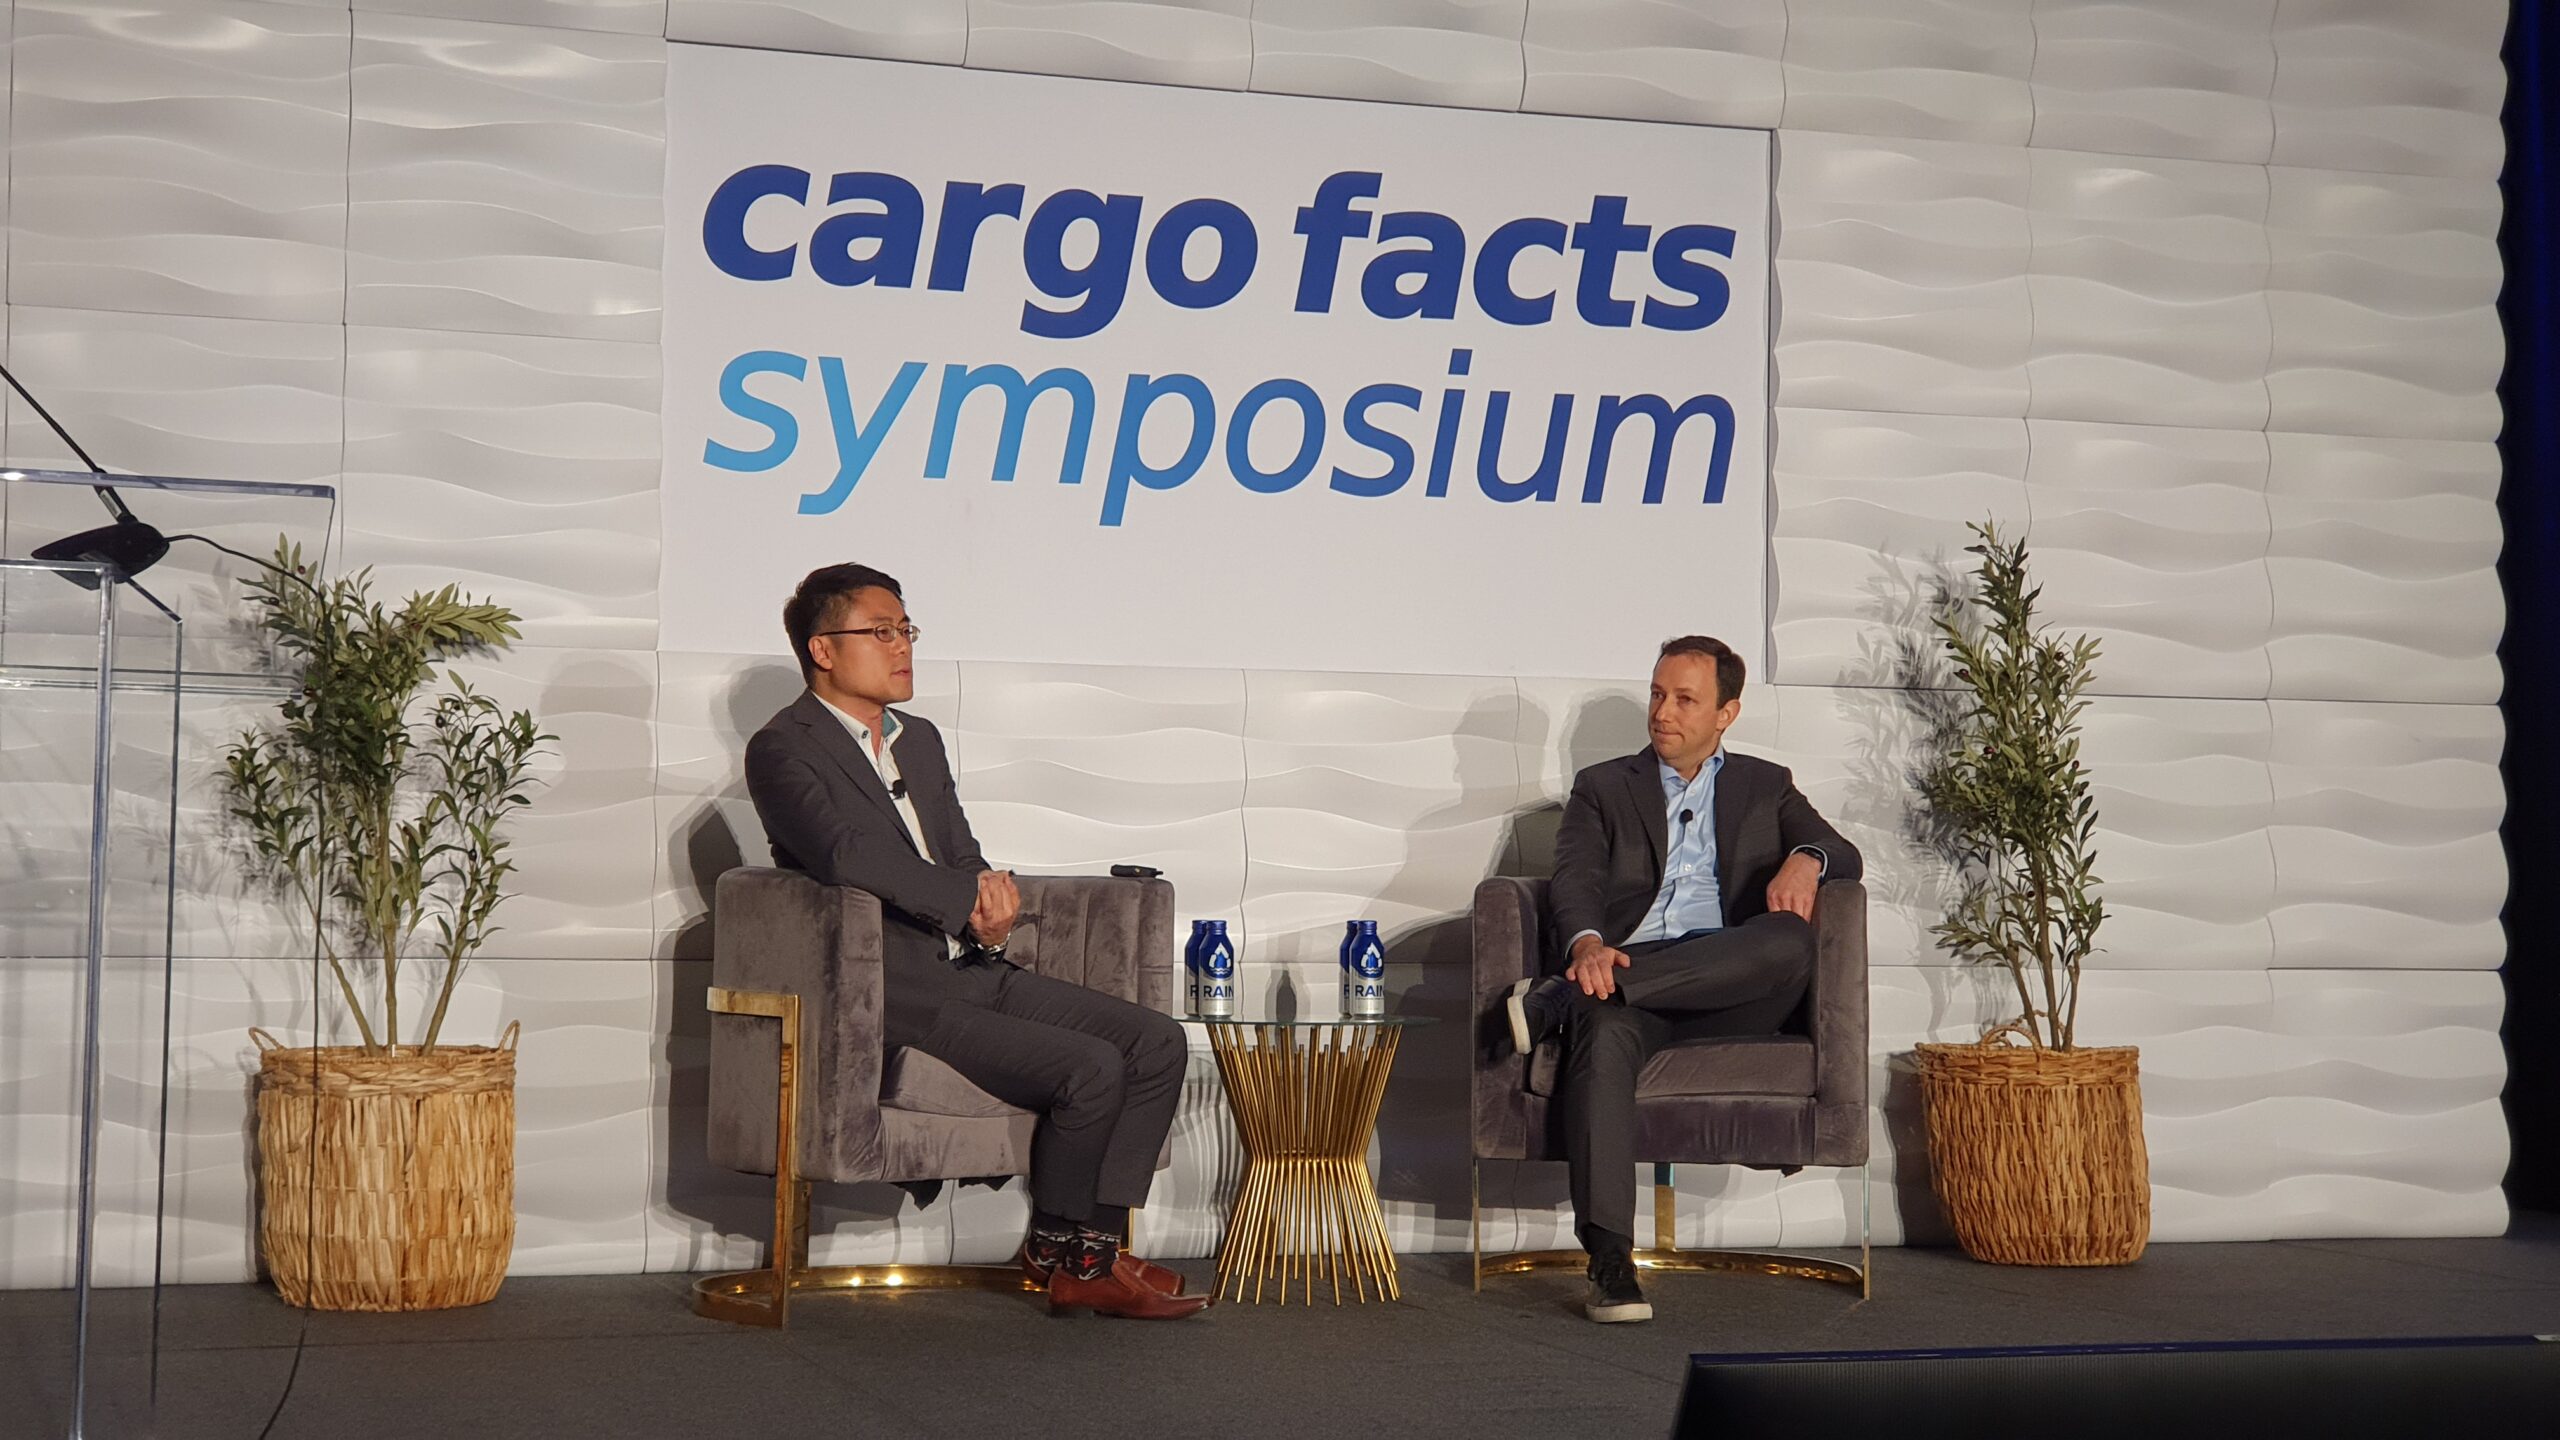
Cargo Facts Consulting (CFC) expects overall cargo fleet growth of about 2.14% per year, with the number of large widebodies such as the Boeing 777F increasing fastest, followed by medium widebodies, narrowbodies and finally smaller aircraft for thinner regional or feeder networks.
This year, the airfreight industry has been hit by several shocks, most notably because of the conflicts in the Middle East — a crossroads of cargo lanes. The choke on the flow of oil out of the Persian Gulf has made jet fuel prices skyrocket, forcing companies to reassess their networks.
While cargo air traffic as measured in cargo-tonne kilometers (CTKs) grew by 4.6% year over year in the first eight months of 2026, CFC Interim Director Jordan Frohlinger said he expects the end of the year to be “considerably softer,” leading to an estimate of 1.5% growth for the year.
“The story is effectively that shippers are being squeezed, fuel prices remain elevated, inflation has picked up here in the U.S. and interest rates are slowly moving higher,” he said. “And each of those takes a little bite out of discretionary spend.”
CFC has debuted a new measure designed to help clients better evaluate the industry and the risk they carry: the “air-to-ocean ratio.” That measures the price fluctuations between ocean-bound cargo transportation versus potential air freight costs. In recent months, the relative price signal has turned to air’s favor. Ocean shipping rates have shown more volatility than airfreight, making airfreight, with prices that have remained in a narrower band, a more viable option for shippers.
“From February to September, air rates are up roughly about 20%, but ocean rates are well up over 100%,” Frohlinger said. “So that matters because the shippers don’t necessarily buy air in isolation; they buy it relative to the alternative.”
Stay up to date on all the news coming out of Cargo Facts Symposium here.

Cargo Facts Free Newsletters